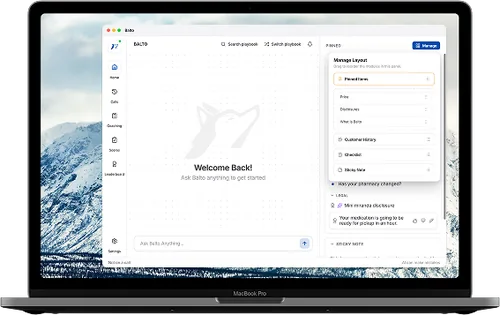
Helping credit unions deliver better customer service to their members
Bankers verify the caller, then handle whatever comes: a fraud claim, a fee question, a hold, a lost card. Each one has its own rules, its own clock, and a customer waiting. Balto puts the procedure on screen with its source, keeps verification and disclosures on a checklist, and writes the record. No hold, no transfer.
Banking isn't one call
A card-dispute call, a fee question, and a fraud claim don't follow the same rules. But all of them run under exact, unforgiving regulations, for a customer who just wants a straight answer.
Reg E and the clock
A debit, ATM, ACH, or Zelle dispute runs under Regulation E; a credit card dispute runs under the Fair Credit Billing Act. Different process, different clock. Get the path or the timeline wrong and it's a compliance problem, not just an unhappy customer.
Holds, fees, disclosures
Funds availability is Regulation CC, account disclosures and APY are Regulation DD, and you can't mislead a customer about a fee without straying into UDAAP. The customer just wants a straight answer.
GLBA at hello
You can't share account information until you've verified identity under GLBA. Every call has to lock that step before anything else, and keep a clean record after.
Everything the banker needs, on the call
The customer's account history is on screen at hello. Verification and required disclosures sit on a checklist. The exact Reg E or FCBA procedure and its current clock are one lookup away, with the source. The notes write themselves.
It reaches the bankers who usually ignore agent assist
A veteran teller won't stop to type for something they feel they know. The passive history and the locked steps are push help, so they reach your veterans and your new hires alike.
Won't stop to type
Verification and routine service are second nature. What no one keeps straight is the exact Reg E versus FCBA path and the current clock on a messy dispute, and that's fair game for a cited lookup. The passive win is account history at hello and the notes written for them.
Learning the dispute rules
The dispute rules and disclosures are a lot to learn. They lean on the lookup, and the locked verification and disclosure steps keep them compliant before they have it down. History gives them context they can't infer.
Makes the right moves routine
Consistency on verification, the right dispute path, and a referral step you can add, so a service call becomes a relationship without a hard sell.
Covered without training
Verification prompts, disclosures on the checklist, history at hello. The thin view keeps it to the basics for people who want it quiet.
For managers
Your exam risk lives in the exact moments a banker can get wrong.
- lockLock verification and required disclosures so they happen every call.
- insightsSee how bankers word the parts they can change, including UDAAP-adjacent fee talk.
- sync_altNotes give you the audit trail an examiner asks for.
- groupsAdd a referral step across the floor and measure whether it's happening.
Why it's different
A lot of exact, changeable rules, and a veteran staff who won't stop to type.
- request_quoteThe exact Reg E vs. FCBA procedure and clock, cited to its source.
- visibilityAccount history that just appears, so veterans don't stop to type.
- edit_noteLocked disclosures and notes that build the record as the call happens.
- groupsReaches your veteran tellers and your new hires, not half the floor.
Ask your call data a question, then ship the fix
Kodi reads every call and answers in plain language, with the calls to back it up. Agentic Insights finds the pattern costing you the most and turns your best bankers' approach into guidance for everyone.
Every banking call scored against your scorecard
Not a sample your team hand-scores weeks later. 100% of calls read the same day, against the criteria your compliance team uses, with verification and dispute-path steps flagged the moment they're missed.
The exact investigation window and provisional-credit rule surface on the call, so a banker follows the right one every time.
Every call checked for verification and the right dispute path the same day, with exceptions routed automatically.
BrightBridge Credit Union brought new-agent ramp from 180 days to 90 with Balto playbooks.
FAQs
Ask whether it can pull the exact Reg E versus FCBA procedure with the source, whether required disclosures fire as locked steps, and whether the notes build an audit trail. Then the quiet question: do your veteran tellers use it, or just the new hires? If it’s a search box the veterans ignore, you’re covering half your floor.
The banker pulls the exact procedure from your own documents, with the source, so they follow the Reg E path on a debit dispute and the Fair Credit Billing Act path on a card dispute. The investigation window, provisional-credit rule, and liability tiers surface on the call. Every call is scored against your scorecard the same day, so you can show an examiner the steps happened.
All three. The same things carry across: the right procedure and the required step in front of the banker live, questions answered on the call, and the notes handled. A service call gets the disclosure and fee language; a fraud claim gets the verification and dispute path in order.
In your core or CRM, as a structured record instead of a scribble. The fields you care about are captured during the call and written back automatically, which gives you the audit trail without after-call typing.
No. The passive help reaches them without training: account history at hello, verification and disclosures on the checklist, notes handled. Overflow and part-time bankers can run the thin view and stay covered on the compliance moments.
See Balto on one of your calls
Bring a real card-dispute or account-service call. We'll show you the account history at hello, the right dispute path and clock on screen, and the notes writing themselves.
Book by phone
+1 (405) 864-4645Call and speak directly with our AI agent to schedule your demo, available 24/7, no wait time.
Call Now